Veterinary QuickBooks CleanupThe bank and the visits disagree
A full clinic day can still leave a deposit the bank will not explain.
Steven Palmieri, a Tax CFO and the Entrepreneur's CFO, sorts that deposit with you until the month can close.
Start with the month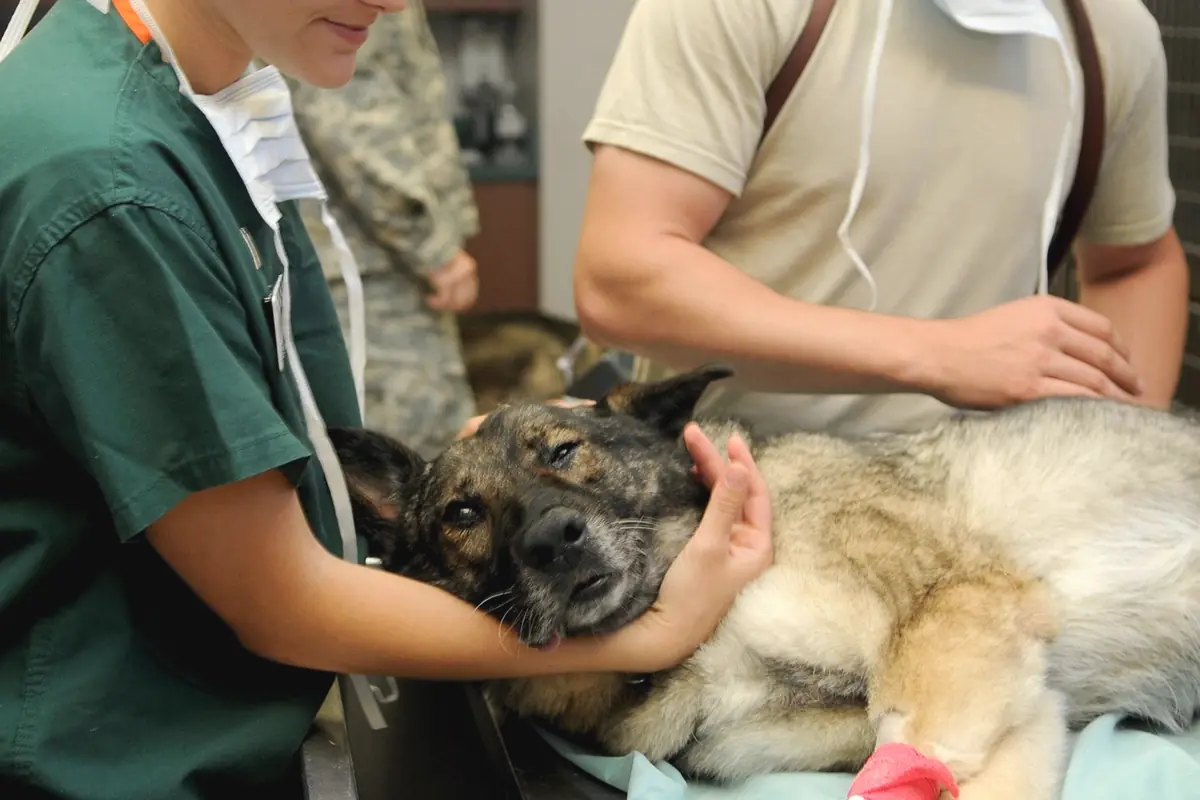
The table is cleared between visits. The deposit still needs a story.
Name the month still open

You will be talking to the Steven Palmieri practice.
The shelf and the screen
A count on the shelf and a count on the screen can disagree even when the day felt complete.
Click to open the shelf ›Tap to open the shelf ›
The deposit that came in short
The bank can show less than the card batch because the processor kept a fee on the way in.
Click to open the deposit ›Tap to open the deposit ›Payday stays with a provider
We prepare the wage file. The provider the clinic already chose is the one that runs payday.
Click to open the wage file ›Tap to open the wage file ›
A month needs a last day
The month can close only after the bank matches, and that closing date then stays put.
Click to open the close ›Tap to open the close ›Questions that show up first
Most of the mess is one of a few snarls. Read the short answers before you send a month.
Click to open the questions ›Tap to open the questions ›Who sits with the owner
One practice reads the clinic month with the owner, and the return is built only from months the bank already agrees with.
Click to open who we are ›Tap to open who we are ›Six snarls we open first.
Tap a snarl. The note under it says what we look at in the file, and what we leave alone.
1One income line for the whole day
We sit with the owner and split the day.
The visit, the bag of food at the counter, and the card batch that night do not become one fact just because they share a deposit. Medical work, a cosmetic bath, a prescribed drug, and a counter good belong on their own lines before anyone asks a state about tax.
2The bank is short of the batch
We lay the batch beside the deposit.
The processor often keeps a fee before the money arrives, so the bank is short of the screen for a reason you can name. That fee needs its own line. A holding account for money still on the way is not income a second time.
3The shelf and the screen disagree
We count what is still in the building.
Food and goods on the shelf are an asset until they are used in a visit or sold at the counter. They are not an expense on the day the carton arrived. A count that will not tie stays on a list instead of being forced to match.
4A plan was paid up front
We ask which visits are still owed.
A wellness plan collected today is not earned on the day the card ran. The care is earned as those visits happen. Until then the clinic still owes the care, and the month should not treat the payment as already finished.
5A relief doctor was paid
We ask which paperwork that doctor uses.
A visiting doctor who is not on the payroll is not the same paperwork as a doctor the clinic employs. The January list for a visiting doctor is usually due by the last day of January. We do not guess the form from a nickname, and we do not put private numbers on this website.
6The month has no last day
We reconcile, and then we stop.
The month can close when the bank matches the file. After that the closing date stays. Changing a month that already left with a return moves numbers the return already used. Write the correction into the month you have not closed yet.
Steven Palmieri, Tax CFO.
The Entrepreneur's CFO. We close a clinic month with the owner, and the return sits on months that already match the bank.
Tell us what the deposit missed
Tell us which deposit did not match the visits, and which month is still open.
You will be talking to the Steven Palmieri practice.
Read the month before you send it
What the deposit is hiding
A full day of appointments can still end with a deposit the bank will not explain by itself. The screen shows visits. The bank shows one amount. Between those two pictures a processor fee, a refund, and a payment for care that has not happened yet can all be sitting in the same number.
We start by laying the day's visits next to that deposit, not by renaming the income account. If the amounts will not meet, the difference gets a line of its own. A line you can point at is more useful than a month that looks smooth and is not.
Payday itself stays with the provider the clinic already chose. That boundary matters even on a deposit page, because a payroll draft can land in the same bank account and look, for one afternoon, like a patient payment that never was.
Nothing on this page uses a real clinic's dollars. The shape is the lesson. Your file supplies the amounts when we open the month with you.
Why the shelf is its own count
Cartons arrive, get used in exams, and get sold at the counter. If the books expense the carton on the day it arrives, the month looks expensive in the quiet week and cheap in the busy one. The shelf is an asset until the item is used or sold.
A count that will not match the screen is not a reason to edit the screen until it looks obedient. We leave the difference on a list with a date. The next count either explains it or it stays visible. Forcing the two numbers together hides a loss you may still be able to find.
Cosmetic bathing, a drug that was prescribed, food, and a leash are not one kind of thing because they left through the same door. A state often taxes those kinds differently. We do not invent the state's answer. We keep the kinds apart so the answer has somewhere true to land.
What we leave with the provider
The wage file is ours to prepare. The paycheck is not. A clinic that already has a payroll provider should not grow a second one inside a book cleanup. We make the file ready, including which people are employees and which visiting doctors are not.
The January list for a visiting doctor is usually due by the last day of January. An employee does not go on that same list. Mixing them is how a year starts with a letter. We ask the question in ordinary words before the list is built.
Estimated payments, for a practice that pays them, often land in April, June, September, and the following January. We write those four months onto the clinic close before deposit week, so an estimate sitting in the operating account is not booked as a visit that never happened. The amounts are the owner's to decide with the return. We do not print a sample amount, because a sample amount becomes a rumor.
How a month actually ends
A month ends when the bank and the file tell the same story and someone sets a closing date. After that date, the month is not a scratch pad. A later deposit that explains an earlier day is recorded in the open month, with a note that points backward. The closed month stays.
Editing a period that already left with a return does not only change that period. It moves numbers a return already relied on. We name that risk out loud before a tidy edit is made. The relief is real, and it is written in the month that has not been closed.
A wellness plan collected at the start is the clearest example. The cash arrived. The care did not. Leaving the whole payment in income makes the collection month look wonderful and every later visit look free. We spread the earning as the visits happen, and we say which visits are still owed.
QuickBooks is a mark of Intuit. This cleanup is not written by Intuit. The screen is where the month lives. The work is the matching.
What we will not invent
If a deposit has no visit, no retail sale, and no plan behind it, we do not invent a patient to balance the day. The amount stays unnamed and visible. Unnamed is uncomfortable. It is also honest, and a later note can still name it.
We will not treat animals, and we will not describe a real animal's care. The books are the subject. A photo on this address is a room, a shelf, a sheet, or a patient in general. It is not a case.
Bring the month you stopped trusting, the deposit that would not explain itself, and the shelf if the shelf is the part that feels wrong. The first call is a conversation. The cleanup starts when the scope is in writing.